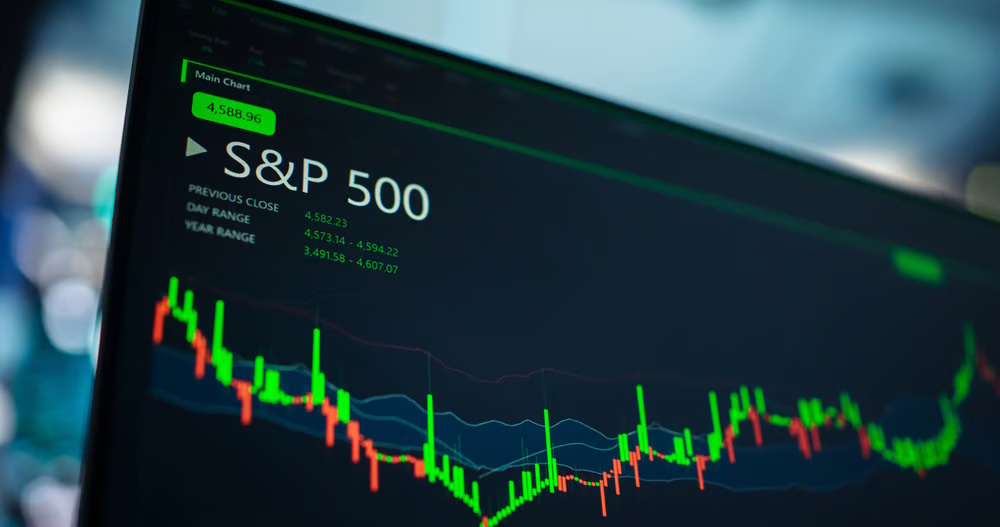
S&P futures exhibited minimal movement on Monday following a week of gains for the major averages, as investors anticipated a week filled with earnings reports and inflation statistics. Futures associated with the S&P 500 experienced an increase of 0.1%, whereas futures for the Dow Jones Industrial Average advanced by 53 points, also reflecting a rise of 0.1%. Nasdaq 100 futures, however, experienced a decline of 0.1%. Oil prices experienced a modest increase in early trading. West Texas Intermediate futures increased by 0.9%, reaching $92.65 per barrel. Brent crude experienced an increase of 0.8%, reaching a trading price of $105.62. Crude prices increased following President Donald Trump’s declaration of a ‘energy ceasefire’ between Russia and Ukraine over the weekend. However, Ukrainian President Volodymyr Zelenskyy subsequently indicated that Moscow had already breached this agreement.
Trump also informed reporters of his contemplation regarding joining Saudi Arabia in its conflict against the Tehran-backed Houthis in Yemen, following yet another lethal assault on Riyadh’s international airport. The remarks raised the prospect of heightened tensions in the region. Wall Street has concluded a successful week for the major averages, driven by a rally in technology stocks that enabled investors to overlook the implications of rising oil prices and yields. The Dow and S&P 500 each recorded their second positive week in three, while the Nasdaq Composite achieved its fourth consecutive week of gains. Investors are optimistic that the upcoming third-quarter earnings season will provide the necessary momentum for stocks to navigate the ongoing turmoil in the Middle East. By all estimations, the forthcoming results are anticipated to be robust.
FactSet’s John Butters indicates that the S&P 500 is poised to achieve an earnings growth rate of 29.6% for the quarter. That would mark the fourth consecutive quarter in which the broader index achieves earnings growth exceeding 25%, driven by the robust expansion of AI data centers. However, it is the statements made by managers that will hold greater significance for investors, considering the ambiguity surrounding how businesses and their customers are navigating increased fuel and borrowing expenses. “Investors have kind of narrowed in on some of the important aspects,” said Brian Leonard. “Can this company withstand what’s happening? Pass along, continue to grow margins, and the future is going to be better than the most recent past.” The reporting season will intensify this week as major financial institutions prepare to release their earnings.
Bank of America, Citigroup, Goldman Sachs, JPMorgan Chase, Morgan Stanley, and Wells Fargo are all anticipated to announce their results during this period. Key inflation data is set to be released this week, with the consumer price index for September scheduled for Wednesday and the producer price index on Thursday. Across the Atlantic, the pan-European Stoxx 600 registered an increase of 0.4%. The U.K.’s FTSE 100 experienced an increase of 0.6%, while the Italian FTSE MIB saw a rise of 0.7%. Germany’s DAX increased by 0.7%, while the French CAC 40 experienced a rise of 0.2%. In Asia, South Korea’s Kospi experienced a decline of 3.65%, whereas the small-cap Kosdaq saw a more pronounced drop of 4.83%. Australia’s benchmark index experienced an increase of 0.76%. Mainland China’s CSI 300 finished the day down by 0.68%. Markets in Japan were closed for a holiday.