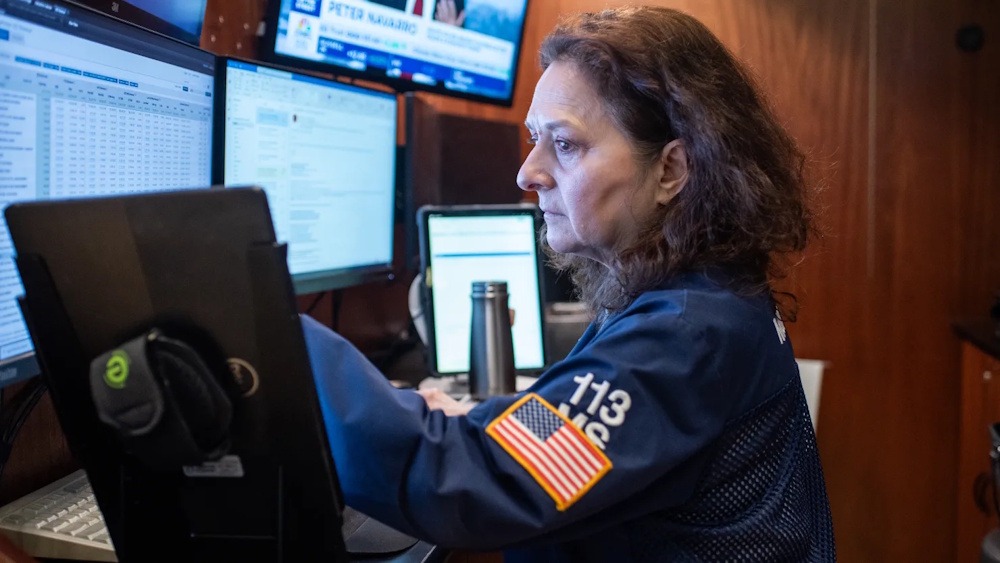
S&P futures advanced in early trading on Monday following a downturn in the previous week on Wall Street, as investors prepared for a week filled with earnings announcements, employment data, and the approaching midterm elections. S&P 500 futures exhibited an increase of 0.49%, whereas Nasdaq-100 futures recorded a rise of 0.82%. Futures associated with the Dow Jones Industrial Average increased by 248 points, representing a rise of 0.48%. The moves follow a week of declines for the three major averages, weighed down by selling pressure in the technology sector as investors maintained a critical eye on companies associated with the artificial intelligence expansion. The S&P 500 and Dow Jones Industrial Average experienced declines of less than 1% over the week, whereas the Nasdaq Composite saw a more significant decrease of 2%.
The week commenced positively following Anthropic’s public filing for an IPO, which provided a lift to AI-related equities. However, selling pressure resumed later in the week amid indications that capital expenditure spending could be diminishing after both Alphabet and Microsoft reported lower-than-anticipated capital expenditure forecasts. Amazon also maintained its full-year capex guidance. Nonetheless, Warren Pies of 3Fourteen Research expresses a measured optimism, highlighting an increase in forward earnings estimates and noting that “there’s a lot to like” about Anthropic’s S-1 filing. “I just don’t see anything broken with the AI trade fundamentally,” he said. “Technicals are another story.” The tech-heavy Nasdaq and the S&P 500 logged a losing October amid AI spending concerns, with the Nasdaq suffering its worst losses since March 2025.
The Dow, however, rose almost 2% as investors rotated into defensive areas like healthcare. “Rather than running for the hills amid heightened AI risks, investors are seeing plenty of return potential in other types of stocks,” Mike Dickson said in a note last week. Dickson added that while this week’s midterm elections “have some investors worried that changes in Washington, D.C., could impact the markets, it’s important to remember that stocks tend to stay steady regardless of which party gains control of Congress.” The elections will occur on Tuesday, with expectations that Democrats will gain control of the House of Representatives, whereas the outcome for Senate control remains ambiguous. Investors are anticipating the release of October’s nonfarm payrolls reading on Friday, which is projected to indicate an increase of 55,000 jobs for the month, as per economists surveyed by Dow Jones.
Alongside the highly scrutinised monthly jobs report, a new series of earnings releases is set to occur this week. Apple, a member of the “Magnificent Seven,” is set to report after the bell on Monday. McDonald’s and Qualcomm are scheduled to announce their earnings later this week. In Europe, the Stoxx 600 benchmark was observed trading nearly 0.1% higher, marking a reversal of earlier losses. France’s CAC 40 advanced by 0.29%, while Germany’s DAX increased by 0.22%. The U.K. FTSE 100 experienced an increase of nearly 0.1%. In Asia, Japan’s Nikkei 225 gained 0.33% to 63,081.86, while South Korea’s Kospi led gains with a 2.38% rise to 5,859.08. Australia’s benchmark S&P/ASX 200 declined by 0.53%. Hong Kong’s Hang Seng index gained 0.44% in its last hour of trade, while mainland China’s CSI 300 added 0.79%.