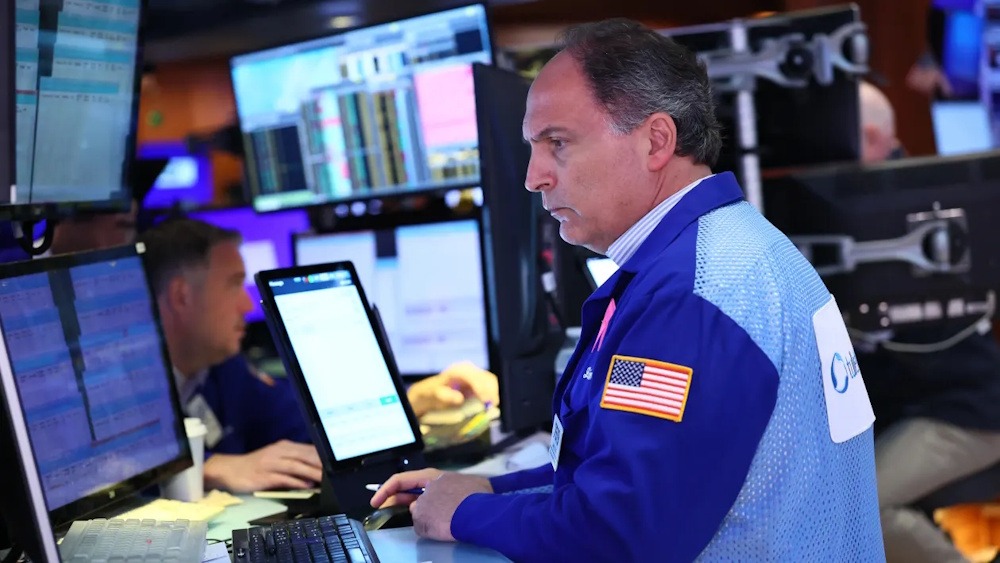
S&P futures experienced a significant decline on Thursday, driven by rising apprehensions regarding excessive expenditures by technology firms on artificial intelligence. Meanwhile, market participants remained on the lookout for forthcoming earnings reports and economic indicators following a session marked by losses. Contracts associated with the technology-focused benchmark declined by 1.1%. S&P 500 futures declined by 0.3%. Futures for the Dow Jones Industrial Average exhibited strong performance, increasing by 139 points, or 0.3%.
CoreWeave shares declined over 5% in the premarket, indicating that the neocloud entity is set to extend the losses observed on Wednesday. The stock tumbled 15% in the previous session as investors grew concerned that the company was excessively leveraging itself for its AI build-out. CoreWeave corporate bond yields experienced a significant increase. Concerns reverberated throughout the broader AI market on Wednesday, resulting in the Nasdaq Composite experiencing its most significant single-day decline since July 23.
Stocks associated with AI, especially those in the memory chip sector, experienced declines on Thursday following a further sell-off in the Korean stock market. Micron shares experienced a decline of 3.7%, while Sandisk saw a drop of 4%. Shares of Sk Hynix listed in the U.S. experienced a decline of 7%. Overnight, South Korea’s Kospi index experienced a decline exceeding 7%. Concerns regarding the Federal Reserve’s potential for a more aggressive tightening of monetary policy before the year’s end are exerting pressure on equities, following the release of new data indicating that consumer prices in September increased at a faster-than-anticipated rate on a year-over-year basis.
“Inflation is cooking with gas,” said Jamie Cox. “It is abundantly clear where the inflation impulse originates, but two wars need to end before we get any relief. The Federal Reserve made the mistake of calling Covid era inflation transitory, and now it appears they are set to make the same mistake in reverse on the energy supply shock.” On Thursday, investors will receive additional inflation data, as the September reading on producer prices is scheduled for release at 8:30 am. New retail sales figures and weekly jobless claims are scheduled for release at that time.