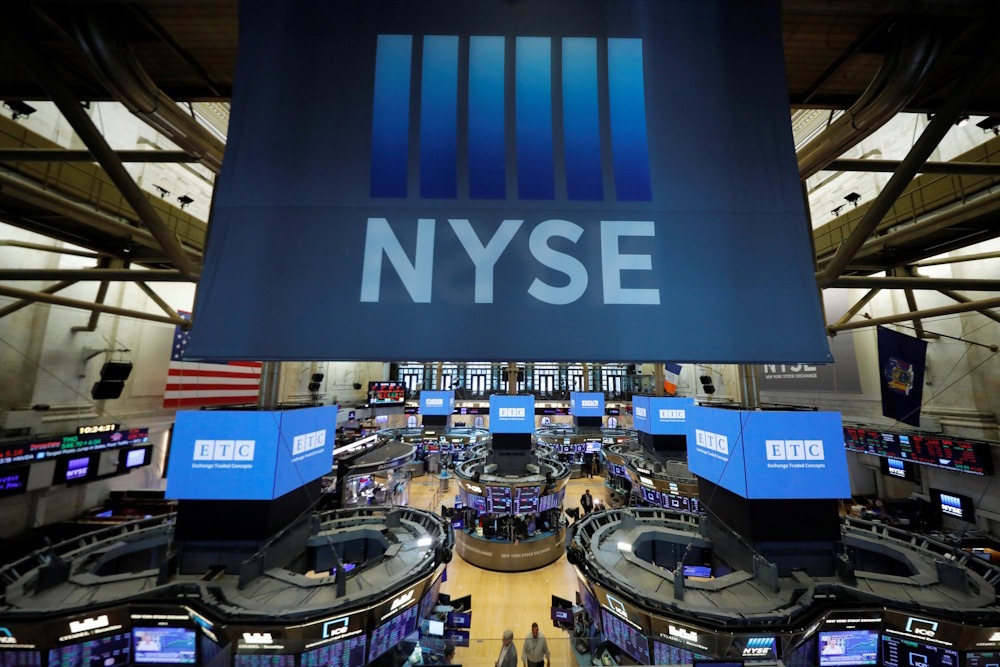
S&P edged lower early Tuesday following a winning session on Wall Street, as traders anticipated a slew of corporate earnings and the commencement of a two-day policy meeting by the Federal Reserve. S&P 500 futures experienced a decline of 0.1%, whereas Dow Jones Industrial Average futures increased by 2 points, hovering just above the flatline. Nasdaq-100 futures have declined by 0.19%. Shares in Nvidia declined by 0.28% during premarket trading following the announcement of a $3 billion investment in Meta. Wall Street commenced the week with a robust performance. The Dow increased by 146.42 points, representing a rise of 0.3%. The S&P 500 gained 0.7%, while the Nasdaq Composite advanced 0.8% as technology shares outperformed. The artificial intelligence trade received a significant uplift following Anthropic’s filing for an initial public offering at the Nasdaq.
This would signify another significant technology initial public offering for 2026, following SpaceX’s blockbuster listing in June. Tesla shares experienced an increase exceeding 5%. Microsoft and Amazon experienced an increase in value on the day. Those gains arise as the artificial intelligence sector has encountered scrutiny from investors concerned that firms within this domain are excessively leveraging debt to finance their AI developments. On Tuesday, market participants will meticulously analyse a substantial influx of third-quarter earnings reports. Coca-Cola, Robinhood, and Boeing are among the firms scheduled to release their earnings reports. Major technology firms Microsoft, Alphabet, and Amazon are scheduled to release their results later this week.
The Fed is poised to commence its latest monetary policy meeting. While the central bank is anticipated to maintain current rates, market participants will seek indications regarding the possibility of an additional rate increase prior to the end of the year. “If, as expected, there is no change in rates, it will still be interesting to see what the vote is after the swings in the last two meetings,” wrote Thomas Block, Washington policy strategist at Fundstrat. “While the Fed views itself above partisan politics, it would be unlikely that the Fed would move rates a week before a national election.” On the economic front, traders will be monitoring durable orders, consumer confidence data, and the new home sales report.
Across the Atlantic, the pan-European Stoxx 600 experienced a decline of 0.35% on Tuesday morning. The U.K. FTSE 100 experienced a decline of 0.99%, marking the most significant loss among European indices, while the French CAC 40 decreased by 0.27% and Germany’s DAX saw a reduction of 0.10%. In Asia, Japan’s Nikkei 225 closed 1.73% higher, while the Topix rose 0.61%. South Korea’s Kospi experienced an increase of 3.09%, whereas the small-cap Kosdaq saw a rise of 2.29%. Australia’s benchmark S&P/ASX 200 experienced an increase of 0.46%. Mainland China’s CSI 300 concluded the trading session with a decline of 1.32%.