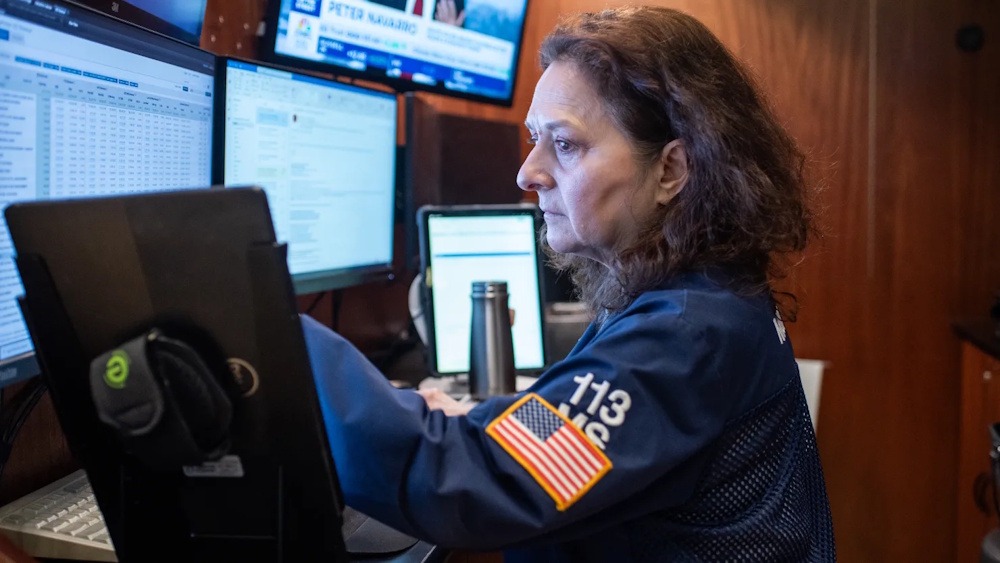
The S&P experienced a decline on Tuesday, primarily driven by the technology sector, following the release of October inflation data that exceeded expectations. Additionally, a significant Federal Reserve official suggested the potential for a half-point increase in interest rates in the upcoming month. The S&P 500 experienced a decline of 0.7%, whereas the Dow Jones Industrial Average fell by 249 points, reflecting a decrease of 0.5%. The Nasdaq Composite experienced a decline of 0.9%. The consumer price index increased by 0.4% in October, surpassing the anticipated rise of 0.3% projected by economists surveyed by Dow Jones. Core CPI, which excludes volatile food and energy costs, rose by 0.3% in October.
Economists had projected a 0.2% increase for the month. Annual figures were not provided for Tuesday’s report due to the 2025 government shutdown. The report followed Fed Governor Christopher Waller’s assertion in a speech Tuesday that he considers a December rate hike probable. He also opened the door for a larger half-point increase next month as inflationary pressures continue to persist. “While the precise timing of the hikes is not of utmost importance, it is crucial that the promised hikes are executed within a reasonable timeframe,” he stated.
Traders currently perceive a December rate hike as almost inevitable, with a minimal probability of a more substantial increase. In a further reflection of the prevailing pessimism, investors have shifted their focus away from technology stocks. Micron Technology and Marvell Technology experienced a decline of 3%, Intel saw a reduction of 2%, and Qualcomm faced a loss exceeding 1%. Nvidia, which did not participate in Monday’s rally after CEO Jensen Huang’s weekend admission of an affair with an alleged Chinese spy, experienced a decline of over 3%.
Anthropic announced its intention to raise up to $64.35 billion in its forthcoming IPO; however, this development did not generate significant enthusiasm for AI-related stocks. The previous session witnessed the S&P 500 achieving its most significant daily gain since April. Those moves followed a tumultuous week for markets, during which traders became increasingly apprehensive about the likelihood of a deceleration in data center construction following significant victories for Democrats in the midterm elections.