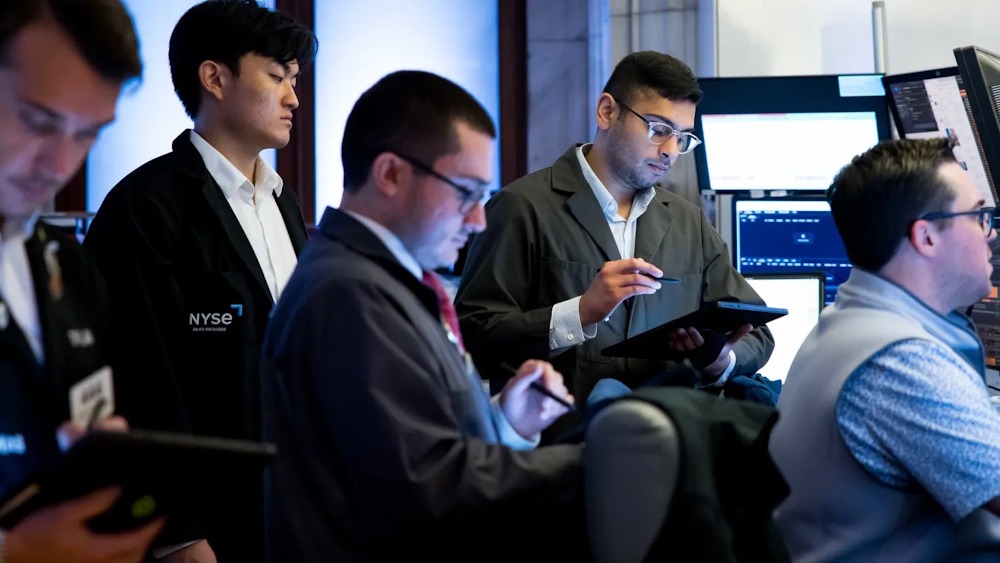
U.S. Treasury yields exhibited a mixed, range-bound pattern on Friday morning, consolidating following a high-stakes central bank marathon as fixed-income desks assessed Federal Reserve Chair Kevin Warsh’s hawkish rate increase in light of a temporary pull-back in global energy markets. The policy-sensitive 2-year Treasury yield, which reflects near-term interest rate expectations, eased slightly to 4.711%, extending its retreat after reaching its highest levels since July 2024 earlier in the week. In contrast, the benchmark 10-year Treasury yield increased slightly to 4.965%, remaining just below the psychologically significant 5 percent threshold it briefly surpassed earlier in the session.
Further out the curve, long-end duration paper attracted a consistent demand. The ultra-long 30-year Treasury yield reached its lowest point in more than a week at 5.297%, retreating from 19-year peaks as investors moved to secure higher yields and factor in possible diplomatic advancements in the Middle East. Fixed-income desks found encouragement in the FOMC’s unanimous 12-0 decision to increase borrowing costs by 25 basis points to a range of 3.75%-4.00%. However, Wall Street strategists observed that front-end rate expectations might have overshot. In a research note, strategists labeled the FOMC developments as firmly hawkish, highlighting that policymakers “did not view financial conditions as restrictive and remain focused on preventing price shocks from generating second-round effects or unanchored expectations.”
UBS cautioned that market pricing at the short end of the curve is looking increasingly overextended, noting that “front-end repricing looks increasingly stretched” with “pricing more than three additional hikes, despite a softer macro backdrop than at the prior 2023 peak.” Long-end yields received further backing on Friday from remarks made by President Donald Trump, who expressed optimism regarding a potential conclusion to the seven-month conflict in Iran. This sentiment was bolstered by reports of intended bilateral discussions with Gulf leaders during the forthcoming UN General Assembly. A 1.5% pull-back in Brent crude futures to $104 a barrel contributed to a reduction in immediate term premia as maritime shipping desks established alternative bypass routes around Persian Gulf shipping bottlenecks.
On Thursday, the Bank of England maintained its key Bank Rate at 3.75% following a split 6-3 vote. However, it cautioned that consumer price inflation might exceed 4 percent early next year, indicating a possible increase to 4% at its November meeting should energy shocks continue. Across the Pacific, the Bank of Japan finalised the central bank triad on Friday by implementing a 25-basis-point interest rate increase to a 31-year high of 1.25%. This move ensures that global capital flows and risk-free borrowing costs remain closely aligned as we approach the fourth quarter.